Mom’s been home from the hospital for three days. Her discharge papers are still on the kitchen table, and you’re trying to figure out how many more mornings you can leave work early to help her shower.
Then the question hits: Doesn’t Medicare pay for this?
It’s one of the most common questions Michigan families bring to us, especially after a hospital stay or when an aging parent begins needing more help at home.
The honest answer: Medicare covers certain medical services at home, but it usually doesn’t pay for the ongoing, everyday help most families are looking for.
Understanding that difference can help you avoid unexpected bills and make a clear plan for your loved one’s care. Here’s what Medicare covers in 2026, what it doesn’t, and what other payment options Michigan families may have.
Quick Answer: Does Medicare Cover In-Home Care in Michigan?
Original Medicare may cover medically necessary, part-time or intermittent home health services for eligible patients, including skilled nursing, physical therapy, occupational therapy, and speech-language pathology.
However, Medicare generally does not cover ongoing non-medical home care when help with bathing, dressing, meals, housekeeping, or companionship is the only help someone needs.
Medicare’s coverage rules are federal, so they apply in Michigan the same way they do everywhere else in the United States. What differs are the other ways to pay: Michigan Medicaid programs, long-term care insurance, veterans benefits, and individual Medicare Advantage plans.
The first step is understanding the difference between home health care and home care.
Home Health vs. Home Care: The Difference That Determines Medicare Coverage
The terms sound almost identical, and families often use them interchangeably. But to Medicare, they describe two very different types of services.
Home Health Care: Skilled Medical Services at Home
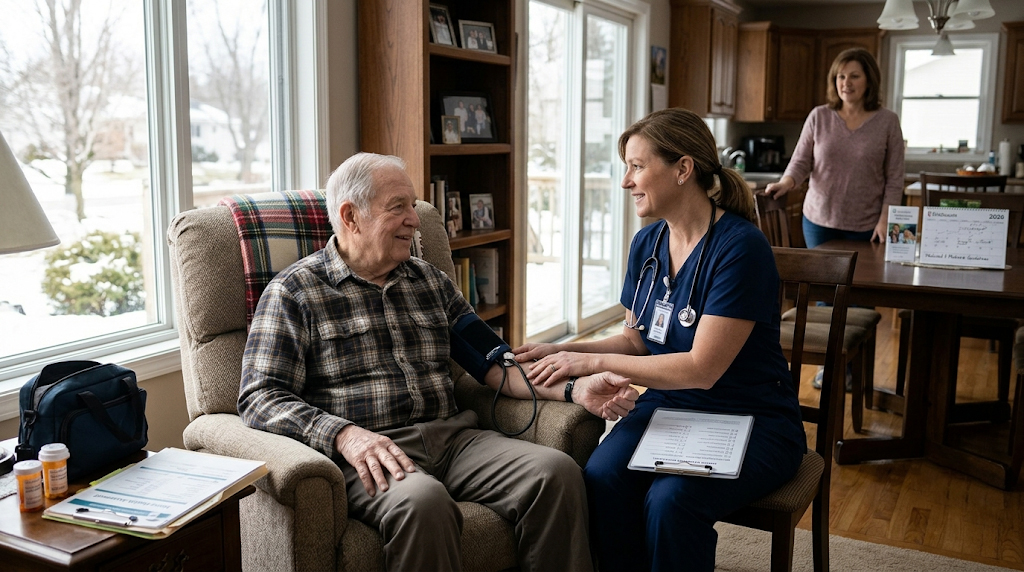
Home health care involves skilled services provided by qualified healthcare professionals under a plan of care established and overseen by an authorized healthcare provider.
Depending on the patient’s needs and eligibility, these services may include:
- Skilled nursing care
- Physical therapy
- Occupational therapy
- Speech-language pathology services
- Medical social services
- Limited home health aide assistance when Medicare’s requirements are met
Home health care often follows a hospitalization, surgery, or change in medical condition. However, Medicare-covered home health isn’t limited to short-term recovery. Coverage can continue as long as the patient continues to meet Medicare’s eligibility and medical-necessity requirements.
Home Care: Non-Medical Help With Everyday Life
Non-medical home care helps older adults manage daily life while staying in familiar surroundings. A trained caregiver can help with:
- Bathing, dressing, and grooming
- Preparing meals
- Light housekeeping and laundry
- Medication reminders (reminders only, not administering medication)
- Rides to appointments and errands
- Companionship and conversation
- Everyday routines and moving safely around the home
These services make daily life more manageable, but Original Medicare generally does not cover them when they are the only type of help needed.
An easy way to remember the difference: Home health helps Dad recover. Home care helps Dad live safely at home, day after day.
Many families need both at different stages of care.
What Do Medicare Parts A and B Cover at Home?
Original Medicare, through Part A and/or Part B, may cover eligible home health services when Medicare’s requirements are met. Covered services can include:
Intermittent Skilled Nursing
Nursing care for qualifying medical needs, such as wound care, certain injections, monitoring a medical condition, or patient and caregiver education.
Physical Therapy
Therapy to address mobility, strength, balance, or other functional needs when skilled treatment is medically necessary.
Occupational Therapy
Services that help patients maintain or improve their ability to perform everyday activities, such as dressing, bathing, and moving safely around the home.
Speech-Language Pathology
Treatment for qualifying speech, communication, or swallowing difficulties.
Medical Social Services
Support with social and emotional concerns affecting the patient’s medical condition or treatment plan.
Home Health Aide Services
Limited help with personal care while the patient qualifies for Medicare-covered home health services and meets Medicare’s aide-service requirements.
Durable Medical Equipment
Certain medically necessary equipment, such as walkers, wheelchairs, or hospital beds, when Medicare’s coverage requirements are met.
Not every patient qualifies for every service. Coverage depends on the individual’s medical needs, eligibility, and approved plan of care.
Who Qualifies for Medicare Home Health Care?
In general, a patient must:
- Be under the care of an authorized healthcare provider who establishes and periodically reviews the home health plan of care.
- Need qualifying skilled services, such as intermittent skilled nursing, physical therapy, speech-language pathology, or continued occupational therapy under Medicare rules.
- Meet Medicare’s homebound requirement. Leaving home must generally require considerable and taxing effort, although certain absences are permitted.
- Receive services from a Medicare-certified home health agency.
- Meet Medicare’s certification and face-to-face encounter requirements.
A person does not necessarily lose homebound status just because they leave home for medical appointments, religious services, or occasional activities.
The healthcare provider and home health agency can help determine whether the patient meets Medicare’s requirements.
What Does Medicare Home Health Cost?
For eligible patients receiving covered home health services under Original Medicare, there is generally no charge for the covered home health visits themselves.
Durable medical equipment works differently. Patients generally pay 20% of the Medicare-approved amount after meeting the Part B deductible.
Other costs may apply depending on the services, equipment, and type of Medicare coverage.
Home Health Aide Hours: What Medicare’s Limits Mean
Medicare does not provide a general weekly allowance for non-medical caregivers.
Home health aide services are covered only when the patient meets Medicare’s home health requirements and the aide services are part of the qualifying care plan.
Medicare generally limits the combined total of covered intermittent skilled nursing and home health aide services to less than eight hours per day and 28 hours or fewer per week. In certain circumstances, up to 35 hours per week may be authorized for a limited period when medically necessary.
These limits do not mean every eligible patient receives 28 hours of aide care. The actual services and visit frequency depend on the patient’s needs.
For example, after hip surgery, Mom may qualify for home physical therapy and limited home health aide help with bathing. Once therapy wraps up and she no longer has a qualifying skilled-care need, Medicare generally stops paying for help with bathing and meals.
If your family is in this stage now, T.O.N.E. Home Care’s sister agency, T.O.N.E. Home Health Services, provides Medicare-covered skilled care at home with nurses and therapists, subject to eligibility.
What Doesn’t Original Medicare Cover at Home?
Original Medicare generally does not cover:
- 24-hour, round-the-clock care at home
- Meal preparation or meal delivery as a standalone service
- Routine housekeeping and laundry
- Companionship
- Transportation to routine appointments or errands
- Ongoing personal care when no qualifying skilled-care need exists
- Long-term custodial care as the only service needed
This is often the biggest surprise for families.
Mom may have finished her prescribed therapy, but she still struggles to get in and out of the shower. Dad may no longer need skilled nursing visits, but cooking and keeping up with laundry have become hard.
Those needs are real, even when Medicare doesn’t cover them. They’re exactly what non-medical home care is designed for.
What About Medicare Advantage? Can It Cover Additional In-Home Support?
Medicare Advantage, also called Medicare Part C, is offered through private insurance companies approved by Medicare.
Medicare Advantage plans must cover the same Part A and Part B services as Original Medicare, but networks, prior authorization rules, and cost-sharing can differ.
Some Medicare Advantage plans also offer supplemental benefits that include limited in-home support for eligible members. These benefits aren’t available in every plan and may be restricted by health condition, eligibility criteria, service limits, or provider network.
What to Check During Medicare Open Enrollment
Medicare’s annual Open Enrollment Period runs from October 15 through December 7. Changes made during Open Enrollment take effect January 1.
If your family is reviewing coverage for the coming year, ask the Medicare Advantage plan:
- Does the plan offer any in-home support benefits beyond standard Medicare home health coverage?
- Does it include help with bathing, dressing, or other daily activities?
- How many hours or visits are available?
- Who qualifies for the benefit?
- Is prior authorization required?
- Must services come from an in-network agency?
- Are there geographic restrictions?
- What out-of-pocket costs might apply?
Review the plan’s Evidence of Coverage and Annual Notice of Change, and confirm benefits directly with the insurer. You can also compare plans through Medicare Plan Compare.
Important: Medicare Advantage supplemental benefits, networks, eligibility requirements, and costs can change from year to year. T.O.N.E. Home Care does not recommend or rank Medicare plans.
How Can Michigan Families Pay for Non-Medical Home Care?
If Medicare doesn’t cover the everyday help your loved one needs, there are several other options to explore. Eligibility, covered services, and payment arrangements vary by program.
1. MI Choice Medicaid Waiver
Michigan’s MI Choice Waiver program may help eligible older adults and adults with disabilities receive long-term services and supports at home rather than in a nursing facility.
Depending on eligibility and the authorized care plan, services may include personal care, homemaking, respite for family caregivers, and other supports. Applicants generally must meet Medicaid’s financial requirements and need a nursing-facility level of care. Openings can be limited, and some areas have waiting lists.
To get started, contact a local MI Choice waiver agency or visit the State of Michigan’s MI Choice Waiver page.
2. Michigan Medicaid Home Help Program
Michigan Medicaid’s Home Help program may help eligible individuals with certain daily living activities, such as bathing, dressing, and meal preparation. Services and hours are based on an assessment of the person’s needs.
Eligibility doesn’t automatically mean every home care agency can provide services under the program, so confirm provider participation and payment arrangements. To learn more or begin the process, contact your local MDHHS office or visit the Michigan Home Help program page.
3. VA Aid & Attendance Benefits
Eligible veterans and surviving spouses may qualify for additional monthly pension income through the VA’s Aid and Attendance benefit, which is meant for people who need help with daily activities like bathing, dressing, or eating.
Aid and Attendance is not an insurance plan that pays a home care agency directly. It’s income paid to the eligible recipient, who can then put it toward care expenses, including non-medical home care.
Learn more through VA Aid and Attendance or talk with an accredited county Veterans Service Officer.
4. Long-Term Care Insurance
Many long-term care insurance policies cover qualifying non-medical home care once the policyholder needs help with activities of daily living or has a qualifying cognitive impairment.
Before arranging care, check:
- What triggers eligibility for benefits
- Any waiting or elimination period
- Daily or monthly benefit limits
- Maximum benefit duration
- Whether the policy covers home care agencies
- Documentation and reimbursement requirements
Contact the insurer to confirm your policy’s specific terms.
5. Private Pay
Many families pay for non-medical home care with savings, retirement income, or contributions from siblings and other family members.
Private pay gives you the most flexibility to choose the hours, schedule, and type of help. Before starting services, ask any provider for a written explanation of rates, scheduling requirements, and any additional charges.
6. Employer and Family Caregiver Benefits
If you’re balancing a job with caring for an aging parent, check with your employer’s human resources department.
Some employers offer caregiver resources, employee assistance programs, backup care benefits, or family leave options. These programs may not pay for ongoing home care, but they can take some weight off your shoulders.
Medicare vs. Private Pay: Who Pays for What?
Use this table as a starting point when exploring care options for a loved one in Michigan.
| Your Loved One Needs | Possible Payment Source | First Step |
| Intermittent skilled nursing at home | Original Medicare or Medicare Advantage, if eligible | Ask the healthcare provider about a home health referral |
| Medically necessary home physical therapy | Medicare, if home health requirements are met | Discuss home health eligibility with the provider |
| Help bathing or dressing without a skilled-care need | Private pay, long-term care insurance, qualifying Medicaid or VA benefits | Explore home care and verify payment eligibility |
| Meal preparation and light housekeeping | Usually private pay; Medicaid programs or VA pension income may help if eligible | Identify the tasks and hours needed |
| Companionship | Usually private pay; VA pension income or long-term care insurance may apply | Review care needs and available benefits |
| Continuous assistance or supervision | Private pay or qualifying alternative programs | Discuss the level of care and available coverage |
| Long-term personal care with limited income | Michigan Medicaid programs (MI Choice or Home Help), if eligible | Contact MDHHS or a local MI Choice waiver agency |
| Daily help for an eligible veteran or surviving spouse | VA pension benefits, including Aid and Attendance | Confirm eligibility through the VA |
| Non-medical help after hospital discharge | Often private pay or another qualifying benefit | Discuss discharge needs and arrange a care assessment |
This table is general guidance, not a coverage determination. Confirm eligibility and benefits with the relevant payer before arranging services.
How T.O.N.E. Home Care Helps Michigan Families With Everyday Care
We know how exhausting it is to balance work, your own family, and a parent who needs more help every month. You shouldn’t have to piece the whole system together at 11 at night.
Families also need a plan for what happens after the nurse leaves, therapy ends, or a parent starts needing more help with everyday routines.
At T.O.N.E. Home Care, we provide personalized, non-medical in-home care built around each person’s routines, preferences, and independence. Our caregivers help with:
- Bathing, dressing, and grooming
- Meal preparation
- Light housekeeping and laundry
- Companionship and meaningful social engagement
- Medication reminders (reminders only, not administering medication)
- Daily routines and moving safely around the home
- Memory care support for people living with Alzheimer’s or other forms of dementia
- Respite for family caregivers
This is the everyday help Original Medicare generally doesn’t cover when it’s the only care needed.
Why Families Trust Us
- Screened, background-checked, bonded, and insured caregivers
- Training in elder care, safety, dementia support, and daily living assistance
- Ongoing caregiver supervision
- Personalized care plans built around your loved one’s routines and preferences
- Part of a family of care services that includes T.O.N.E. Home Health Services, which holds 4-star CMS quality and patient-satisfaction ratings on Medicare Care Compare
When Families Need Both Home Health and Home Care
Sometimes medical care and non-medical help are both important.
For example, after a hospital stay, Mom may receive skilled physical therapy through a Medicare-certified home health agency a few times a week. On the days in between, she may still need help preparing meals, getting dressed, or keeping up with the house. Non-medical home care can fill those gaps.
T.O.N.E. Home Care is part of a broader family of care services that includes T.O.N.E. Home Health Services and T.O.N.E. Hospice. Medicare-covered home health, non-medical home care, and hospice are distinct services, each with its own coverage and payment rules. Hospice is a separate Medicare benefit for people with a serious illness who choose comfort-focused care; if your family is facing that decision, T.O.N.E. Hospice can explain how hospice coverage works.
Serving Families Across Southeast Michigan
Based in Farmington Hills, T.O.N.E. Home Care supports families across Oakland County and nearby Southeast Michigan communities.
If you’re looking for in-home care services in Wayne County, MI, or private-duty caregivers in Oakland County, our team can talk through your loved one’s needs and confirm service availability in your community.
Our goal is to help families make informed decisions about everyday care while treating each person with compassion, dignity, and respect.
Getting Started With T.O.N.E. Home Care
You don’t need to have every answer before reaching out. A family member, doctor, discharge planner, or social worker can contact us. Here’s how it works:
Step 1: Start With a Conversation
Tell us about your loved one’s daily routines, the challenges they’re facing, and the kind of help your family is considering.
Step 2: Schedule an In-Home Care Assessment
We’ll visit your loved one’s home, learn about their routine and safety needs, and talk through scheduling.
Step 3: Build a Personalized Care Plan
Together, we’ll develop a plan that supports your loved one’s comfort and independence, with a matched caregiver and ongoing supervision.
If you’re unsure whether Medicare or another program may help pay for care, we can explain the difference between our non-medical services and Medicare-covered home health care, and point you to the right payer to verify benefits.
Frequently Asked Questions About Medicare and In-Home Care
Will Medicare Pay for a Caregiver for My Mother?
Usually not for ongoing daily help. Original Medicare generally does not cover a non-medical caregiver when personal care, meals, or companionship are the only services needed. Limited home health aide services may be covered while your mother meets Medicare’s home health eligibility requirements, including receiving qualifying skilled care.
How Many Home Health Aide Hours Does Medicare Cover?
Medicare-covered aide services are limited and must be part of a qualifying home health plan. Combined skilled nursing and aide care is generally limited to less than eight hours per day and 28 hours or fewer per week, with up to 35 hours in certain cases. The actual amount of covered care depends on medical necessity and the approved care plan.
Does Medicare Pay for 24-Hour Care at Home?
No. Original Medicare does not cover 24-hour care at home. Home health visits are part-time and tied to a skilled medical need. Families needing continuous help generally explore private pay, long-term care insurance, VA benefits, or Medicaid programs, depending on eligibility.
Does Medicare Cover All Care at Home After a Hospital Stay?
No. A hospital discharge doesn’t automatically qualify someone for Medicare-covered home health services. Eligibility depends on the person’s medical needs and Medicare’s requirements. Ongoing non-medical help may need to be arranged separately, so ask the discharge planner before leaving the hospital.
Does Medicare Advantage Cover Non-Medical Home Care?
Some Medicare Advantage plans offer supplemental benefits that include limited in-home help for eligible members. Coverage varies by plan, so confirm the specific services, restrictions, and costs directly with the insurer.
Does T.O.N.E. Home Care Accept Medicare?
No. T.O.N.E. Home Care provides non-medical home care, which Original Medicare does not cover on its own. Families typically pay privately, use long-term care insurance, or apply income such as VA Aid and Attendance benefits. For Medicare-covered skilled care at home, our sister agency, T.O.N.E. Home Health Services, can help.
Finding the Right Help at Home
Understanding what Medicare covers is an important first step. The next is finding support for the everyday needs that remain.
Waiting too long can mean a worn-out family caregiver, skipped meals, or a fall that might have been avoided. It doesn’t have to go that way.
Picture Mom enjoying a warm lunch at her own kitchen table. Dad reading the morning paper in his favorite chair, with someone dependable nearby. And you, stopping by on Sunday just to visit, not to scrub the bathroom. That’s what the right help at home can do.
At T.O.N.E. Home Care, we believe the right support should help your loved one feel comfortable, respected, and as independent as possible in the place they call home.
Let’s start with a conversation about your family’s needs.
Call (248) 536-2915 or contact us online to talk through non-medical home care options and schedule an in-home care assessment.
T.O.N.E. Home Care, Inc. 33742 W 12 Mile Rd, Suite A1 Farmington Hills, MI 48331 Phone: (248) 536-2915 Website: https://tonehomecare.com/
Coverage information: This article provides general information about Medicare and other payment options in 2026. Benefits depend on eligibility, medical necessity, and individual plan or program rules. Confirm current coverage with Medicare, your health plan, Medicaid, the VA, or the relevant insurer before arranging services.